
The Best Options for Bad Credit Loans in Texas: A 2026 Ranking
The Best Options for Bad Credit Loans in Texas: A 2026 Ranking
Last updated: 2026-10-17
Trying to manage money in Texas can feel like driving through a sudden thunderstorm without wipers. When your credit score isn’t where you want it, finding a lender feels less like a stroll and more like a marathon. You need more than a quick cash injection; you need a lifeline that won’t pull you under.
Whether you are facing a sudden transmission failure in Houston or an unexpected medical bill in Dallas, the stakes are high. The temptation to grab the first offer is strong when you are under pressure. You want a solution that actually helps instead of adding to the chaos.
This list is for Texans facing unexpected hurdles, from auto repairs to medical bills. Choosing the right lender requires looking past the glossy advertisements to find actual stability. We focused on finding institutions that prioritize accessibility and transparency, ensuring you can rebuild your footing without falling into a debt trap.
In a state where the cost of living fluctuates wildly between major cities and rural counties, knowing your options is your best defense. Understanding the fine print helps you avoid predatory lending practices that target those in a pinch. Knowledge is the best way to keep your finances on track.
- Texas Bay Credit Union
- Solarity Credit Union
- TexasLoansToday
- Wisetack
How Texas Lenders Were Evaluated
Finding the right fit for bad credit loans in Texas isn’t just about finding the fastest money, though speed certainly helps. It is a balance between how easy it is to get approved and the long-term cost of that debt. A lender that says “yes” too easily might be charging interest rates that will keep you broke for years.
We analyzed the fine print of various lending models. We compared the Annual Percentage Rate (APR) against the speed of disbursement to see which lenders offer the best value for immediate needs versus long-term health. Speed is great, but it shouldn’t come at the cost of your future income.
The comparison focused on several key areas: the ease of the application, the speed of funding, and the flexibility of terms. We looked for lenders that serve a wide range of Texas cities and those that offer specialized products like credit builder options. Every entry was vetted to ensure they provide genuine service to those with less-than-perfect credit histories.
We specifically prioritized lenders that offer “soft pulls” for pre-qualification. This allows Texans to shop around without the penalty of a hard inquiry on their credit report. When your score is already fragile, avoiding unnecessary hits to your report is a crucial factor in maintaining stability.
| Lender Name | Loan Amounts | Funding Speed | Credit Impact | Best For |
|---|---|---|---|---|
| Texas Bay Credit Union | Up to $2,000 (Starter) | See site | See site | Building Credit |
| Solarity Credit Union | See site | See site | See site | Business & Personal |
| TexasLoansToday | $500 – $35,000 | 24 Hours | No Hard Pull | Fast Funding |
| Wisetack | See site | Under a minute | See site | Home Services |
Top Ranked Texas Lenders for 2026
1. Texas Bay Credit Union
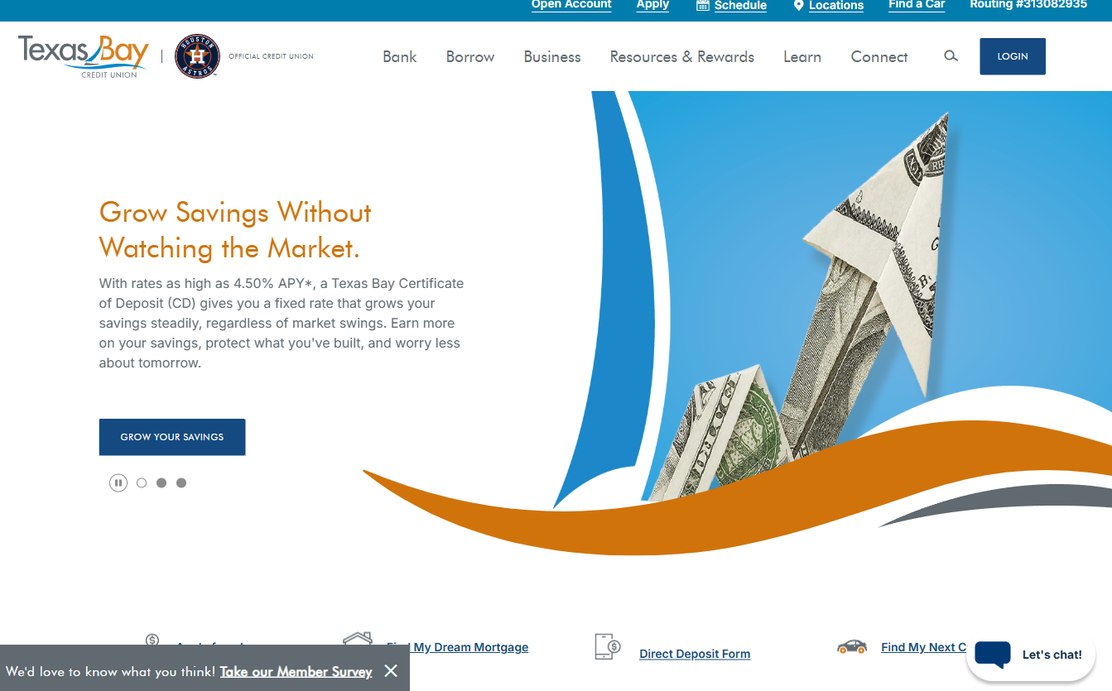
Texas Bay Credit Union acts as a steady hand for those just starting their financial journey. They offer specialized starter loans designed specifically for individuals with little to no credit history. These loans are capped at $2,000, which makes them an excellent entry point for anyone looking to prove their reliability to future lenders.
Unlike traditional big-box banks that might automatically reject a profile with a thin credit file, Texas Bay looks at the broader picture of your financial stability. They understand that everyone starts somewhere, and they provide the tools to help you move forward from that starting point.
Beyond basic credit building, they provide options like auto financing to help you stay on the road. Their products are built to be flexible, ensuring that your budget isn’t stretched to a breaking point. For example, their auto financing programs are tailored to help you secure reliable transportation without the predatory interest rates often found in “buy here, pay here” lots.
Pros:
- Starter loans specifically for building credit.
- Flexible auto financing options.
- Established credit union stability.
Cons:
- Starter loan amounts are limited to $2,000.
2. Solarity Credit Union
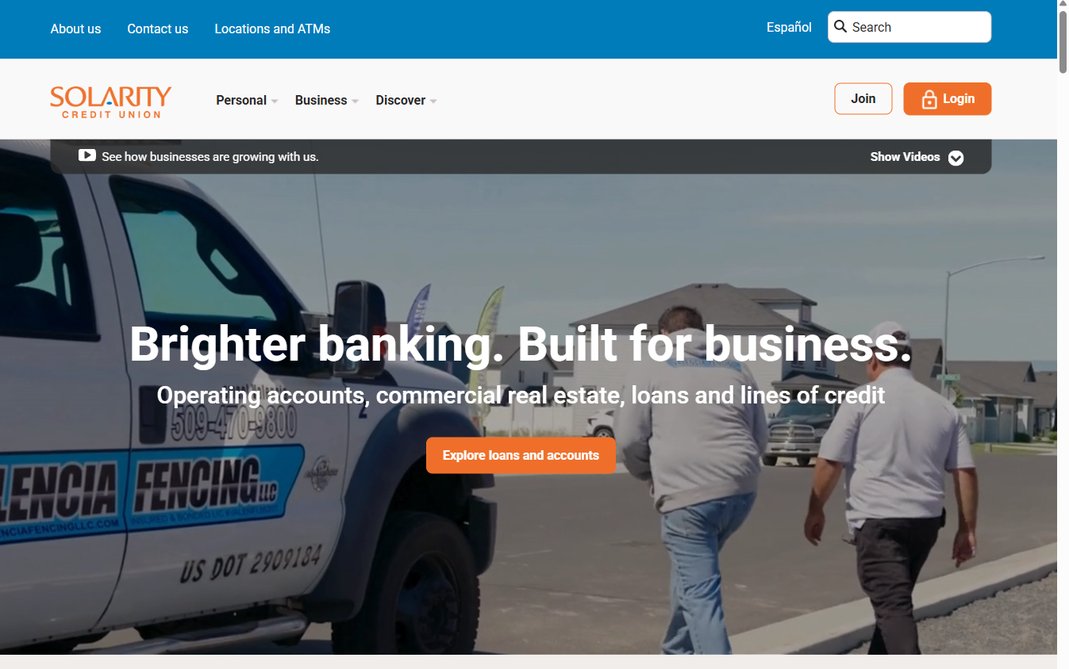
Solarity Credit Union approaches banking with a focus on brightness and simplicity. They cater to a wide demographic, from individuals needing personal support to businesses looking for commercial real estate or lines of credit. Their model is built around providing guidance alongside modern digital tools.
They aim to fill the gap between the convenience of a fintech app and the security of a traditional financial institution. If you are looking to manage both personal and business needs, Solarity offers a comprehensive suite of services. They emphasize a “brighter” banking experience, which translates to knowledgeable employees who actually take the time to listen.
Whether you are a small business owner in Austin trying to expand your inventory or a resident in San Antonio looking to consolidate high-interest debt, their consultative approach helps you map out a path forward. They do more than just hand you a check; they help you understand the implications of your financial choices.
Pros:
- Wide variety of business and personal products.
- Emphasis on expert guidance and support.
- Modern digital banking tools.
Cons:
- May require more traditional documentation than online-only lenders.
3. TexasLoansToday
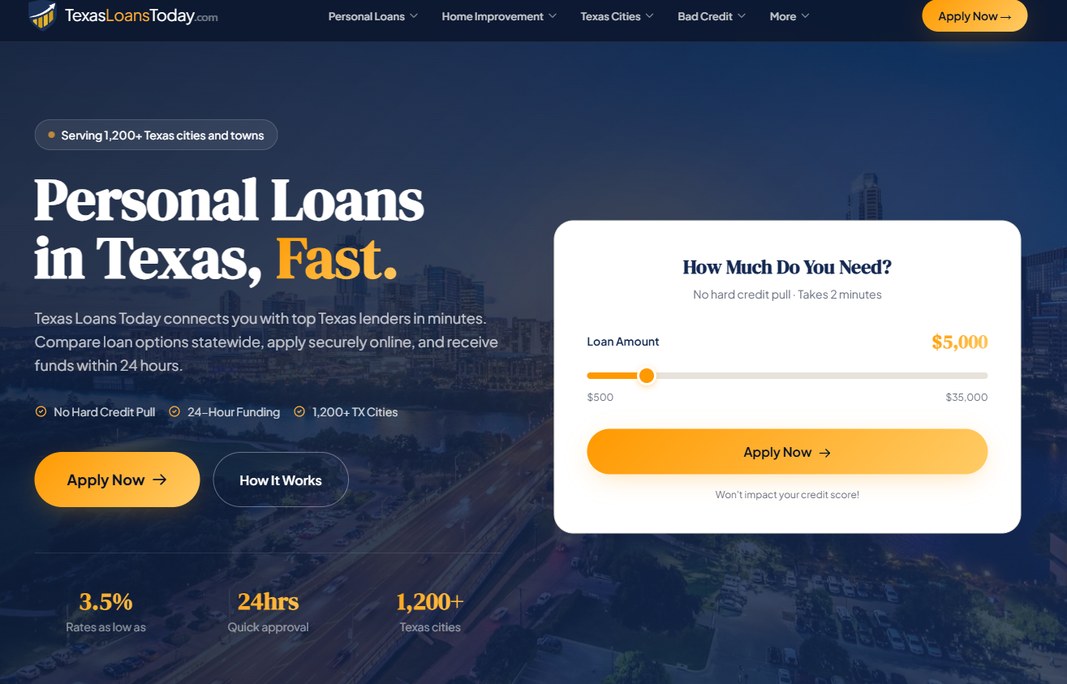
When time is of the essence, TexasLoansToday steps up to the plate. They serve over 1,200 Texas cities and towns, making them a true statewide powerhouse. Their primary advantage is speed, often providing a decision on your application within a single day through a very streamlined process.
In emergencies—such as a sudden plumbing crisis or an urgent repair needed to keep a vehicle on the road for work—this speed can be the difference between stability and catastrophe. They are built for those who cannot afford to wait weeks for a bank’s committee to meet.
This lender is particularly friendly to those worried about their credit score. They offer a “no hard credit pull” option, meaning you can check your rates and see what you qualify for without any damage to your score. This is a critical feature for those attempting to rebuild their credit, as every hard inquiry can shave points off an already delicate score.
Pros:
- Extremely fast 24-hour funding.
- No hard credit pull during the initial check.
- Wide coverage across Texas.
Cons:
- High interest rate potential for some users.
4. Wisetack
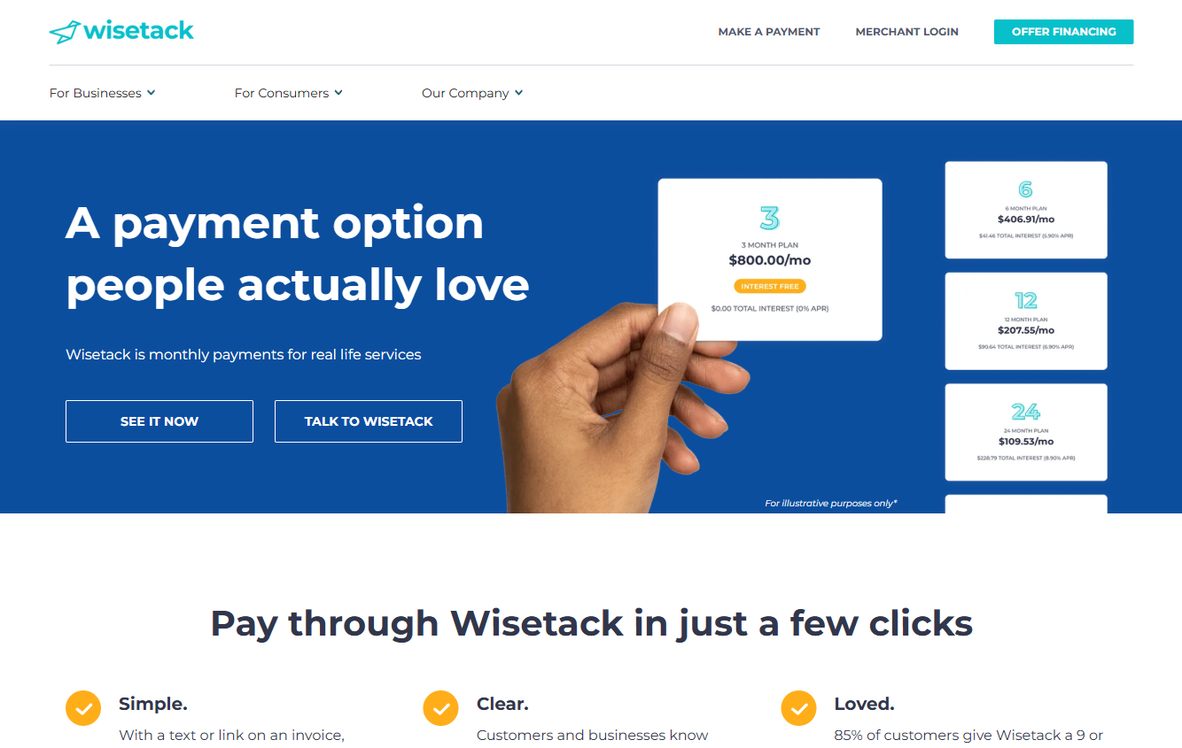
Wisetack operates a bit differently than a traditional bank, focusing on the intersection of consumers and home service businesses. If you need a repair done on your house—such as HVAC work, roofing, or electrical repairs—this is the way to go. It allows you to see your financing options in under a minute through a simple text or invoice link.
This removes the need to fill out lengthy, intimidating paperwork at a bank branch. The beauty of this system is the transparency. Both the customer and the service provider know exactly what the costs are upfront, which eliminates that awkward “sticker shock” at the end of a job.
This integration creates a closed-loop system where the money goes directly to the service provider, ensuring the job is completed and the consumer is protected. It is highly rated by users who prefer a frictionless, digital-first experience that prioritizes clarity over complexity.
Pros:
- Instant visibility of financing options via text/link.
- High customer satisfaction ratings.
- Seamless integration for home service businesses.
Cons:
- Limited to financing specific home service transactions.
Understanding the True Cost of Borrowing
Before signing any agreement, it is vital to perform a mathematical autopsy on the loan terms. Many borrowers focus solely on the monthly payment, but this is a dangerous metric. A low monthly payment often indicates a longer loan term, which can result in you paying double or triple the original amount by the time it is satisfied.
To avoid this, you must look at the Total Cost of Loan. To calculate the real impact on your wallet, use this simple step-by-step method:
- Identify the APR: Do not just look at the interest rate; look at the Annual Percentage Rate, which includes fees.
- Calculate Total Interest: Multiply the monthly payment by the total number of months in the term, then subtract the original principal.
- Factor in Fees: Add any origination fees, processing fees, or administrative charges to that total.
- Compare: Compare this “all-in” number against other offers to see which lender is actually cheaper over the life of the loan.
For example, a $2,000 loan with a 5% interest rate over 12 months is vastly different from a $2,000 loan with a 25% interest rate over 36 months, even if the monthly payments seem manageable in both scenarios. The latter will cost you thousands more in interest, effectively turning a small repair into a long-term financial burden.
Strategies for Rebuilding Credit While Managing Debt
Taking out a loan to cover a current need should not be a permanent setback. In fact, if managed correctly, it can be the catalyst for improving your financial profile. The goal is to use the liquidity to solve an immediate problem while simultaneously implementing habits that prevent the need for high-interest loans in the future.
Consider the following tactical steps to ensure your borrowing experience leads to growth:
- Prioritize Credit Builder Products: If your goal is to fix your score, a specialized credit builder product like those offered by Texas Bay Credit Union is often a much smarter move than a standard installment loan. These products are designed to report positive payment history to the bureaus without requiring a large upfront sum.
- Set Up Autopay: Late payments are one of the fastest ways to destroy a recovering credit score. Even a single 30-day late payment can drop your score significantly. Setting up automatic withdrawals ensures you never miss a due date, even during busy or stressful months.
- Avoid “Credit Stacking”: It is tempting to take out multiple small loans to cover different expenses. This is a recipe for a debt spiral. Instead, look for a single consolidation option if possible, or prioritize the highest-interest debt first using the “Avalanche Method.”
- Review Your Statements Monthly: Don’t wait for a collection agency to call. Regularly checking your bank statements and credit reports allows you to catch errors or unauthorized charges before they escalate into serious legal or financial issues.
Making the Right Choice for Your Wallet
The biggest mistake people make when seeking bad credit loans in Texas is rushing into the first offer they see. It is tempting to grab the quickest cash, but a high-interest loan can quickly become a mountain of debt. Always ask about the total cost of the loan, including all fees and the full APR. A lender who is transparent about these costs is a much safer bet than one who hides them in the fine print of a digital application.
You should also consider whether you need a general personal loan or a specific product like a credit builder loan. If your goal is to fix your score, a specialized credit builder product is often a much smarter move than a standard installment loan. Take a breath, compare the numbers, and choose the path that leads to growth, not a cycle of debt. Your financial future in Texas depends on the decisions you make during these critical moments of need.
